Colorado employers will face new requirements under a law that affects how they handle government-issued identification documents during the hiring and employment eligibility verification process. HB26-1283, which goes into effect on August 12, 2026, restricts how employers handle workers’ and applicants’ identification documents and creates new notice and acknowledgment requirements that employers must incorporate into their onboarding procedures.
The law will have particular significance for multi-state employers. Processes that employers previously standardized across their workforces will now require a Colorado-specific component.
New Requirements in the Form I-9 Process
The law generally prohibits employers and their agents from requiring workers or applicants to surrender government-issued identification documents or from confiscating or retaining those documents, subject to limited exceptions. Employers may continue to examine identification documents for Form I-9 purposes and make copies when permitted, but they may not retain the documents for more than ten hours.
Employers also must provide individuals with written notice describing the law’s protections and obtain an acknowledgment during the I-9 process. Employers must retain the acknowledgment in their employment records.
The Operational Challenge
Employers often use a combination of electronic Form I-9 providers, HRIS systems, and applicant tracking platforms. These systems may not currently accommodate a Colorado-specific notice and acknowledgment requirement. Employers should evaluate whether their existing technology can incorporate the new requirements or whether they need to implement another process.
Consequences for Noncompliance
The law provides criminal penalties for knowing violations of the prohibition against confiscating identification documents, including Class 2 misdemeanor treatment and enhanced penalties for certain bias-motivated conduct.
The law does not appear to establish a specific criminal penalty for failing to provide the required notice or obtain an acknowledgment. Nevertheless, the absence of a specified penalty does not eliminate potential enforcement or litigation risks if an employer’s document-handling practices later come under scrutiny.
Action Items for Employers
Employers with employees in Colorado should begin preparing for the new requirements by:
Reviewing onboarding procedures. Identify where to incorporate the required notice and acknowledgment into the hiring process.
Evaluating technology. Determine whether existing Form I-9, HRIS, applicant tracking, or onboarding systems can deliver the notice, and capture the acknowledgment, and retain the same.
Establishing recordkeeping procedures. Determine where to store acknowledgments and ensure that employers can readily locate them to demonstrate compliance.
Training responsible personnel. Ensure that HR and onboarding personnel understand the new requirements and the distinction between reviewing identification documents and retaining original documents.
Reviewing vendor capabilities. Employers that rely on third-party Form I-9 or onboarding providers should determine whether those providers will offer functionality that addresses the new Colorado requirements.
Employers should work with their HR teams and technology providers now to establish a practical process that documents compliance with HB26-1283.
For questions about this legal alert, please contact a member of Davis Graham’s Employment Group.
Effective August 12, 2026, Colorado’s new retainage bond law (HB26-1311) will significantly change payment dynamics on private construction projects. The law allows contractors on projects exceeding $150,000 to tender a retainage bond in place of cash retainage and requires property owners to accept any bond meeting the statutory standards. This change carries important implications for lenders, property owners, developers, contractors, and subcontractors – all of whom should review their construction documentation, agreements, and procedures. Below is a breakdown of the new law’s requirements, what it means for your organization, and steps you can take now to prepare.
Background
HB26-1311 represents the latest reform to Colorado’s payment and retainage framework in C.R.S. § 38-46-101, et seq. In 2021, the state enacted legislation capping retainage withholdings at 5% of the contract price. With competitive bidding and slim profit margins, contractors have often relied on loans or lines of credit to cover expenses until final payment is released.
Even with the 5% ceiling, property owners and developers can withhold millions on larger projects through the retainage mechanism. HB26-1311 allows contractors to eliminate retainage withholding at their option by tendering a retainage bond, while still providing owners with security through surety bond coverage.
Changes to the Payment Process
Under the new law, tendering a retainage bond is optional for contractors. However, when a general contractor tenders a qualifying retainage bond in lieu of retainage, the property owner must accept it and release the retainage covered by the bond. The general contractor must then accept qualifying like bonds from all subcontractors and release the retainage those bonds cover. For projects exceeding $150,000 where the general contractor has tendered a qualifying bond, general contractors must accept like bonds from downstream subcontractors and suppliers regardless of the subcontract value. These bond acceptance requirements do not apply to contracts for individual single-family homes, multi-family dwellings of four units or fewer, or property owned by a public entity (including contracts resulting from public-private partnerships).
To qualify, a bond must secure both (1) faithful and complete contract performance and (2) full payment to all subcontractors, suppliers, and laborers. Property owners and principal contractors may require the surety to carry a minimum A.M. Best rating, but that minimum cannot exceed “A-.” The surety must also be licensed to issue bonds in Colorado. If a contractor must obtain a bond to secure the release of funds for a subcontractor who has tendered a bond, the contractor may deduct the proportional bond premium from that subcontractor’s final payment. Importantly, the law does not affect an upstream party’s ability to withhold funds or deduct from any payment for backcharges or other amounts authorized by contract.
Considerations
Property owners, developers, lenders, and contractors will need to adjust their contracts and processes to comply with HB26-1311 and to understand the implications of shifting from traditional retainage to bond-based security. The law does not affect existing contracts, but any contract entered into after August 12, 2026, must account for the possibility that a contractor may tender a retainage bond in lieu of cash retainage.
The law leaves several enforcement mechanisms unaddressed, including the claims process and cure procedures. Interparty agreements will need to fill these gaps. Until courts have an opportunity to interpret the statute, questions remain about implementation and whether parties can waive or contract around the right to substitute a retainage bond for traditional retainage.
For questions about HB26-1311, please contact a member of the Davis Graham Real Estate Group.
On July 9, 2026, a division of the Colorado Court of Appeals issued its opinion in Dreifus v. Glenarm Dining Services, Inc., 2026 COA 59, holding that the Ending Forced Arbitration of Sexual Assault and Sexual Harassment Act of 2021 (EFAA), 9 U.S.C. §§ 401–402, applies to an entire “case” rather than to discrete claims, and that retaliation claims arising from the filing of a sexual harassment lawsuit are “related to” the underlying sexual harassment dispute within the meaning of the statute and, therefore, not arbitrable.
The division also held that an employer seeking to compel arbitration under Colorado Rule of Civil Procedure 12(b)(1) must identify specific disputed facts and request an evidentiary hearing—arguments of counsel alone do not create a factual dispute.
Background
Plaintiff signed a broad arbitration agreement as a condition of her employment. After allegedly receiving harassing social media messages from one of her supervisors, she sued her employer, asserting claims under the Colorado Anti-Discrimination Act for sexual harassment, sex discrimination, and retaliation as well as several common-law tort claims.
Her employer did not seek to compel arbitration of the original complaint, conceding those claims involved sexual harassment allegations excused from arbitration under the EFAA. The EFAA provides,
at the election of the person alleging conduct constituting a sexual harassment dispute or sexual assault dispute . . . no predispute arbitration agreement . . . shall be valid or enforceable with respect to a case filed under Federal, Tribal, or State law and relates to the sexual assault dispute or the sexual harassment dispute.
Mid-suit, Plaintiff amended her complaint to add allegations that, after she filed the original complaint, she was placed on administrative leave and terminated in retaliation for filing the sexual harassment lawsuit and for participating as a witness in an unrelated wage-theft investigation. The amended complaint did not add any new claims or alter the original claims.
The employer moved under C.R.C.P. 12(b)(1) to dismiss those claims and compel arbitration of those claims. The employer argued the new allegations were not sufficiently “related to” the sexual harassment claim and therefore fell outside the EFAA’s protections. The district court denied the motion, concluding the EFAA applied to the entire case. The employer filed this interlocutory appeal.
The Division’s Analysis
The EFAA Applies to the Entire “Case,” Where Some, But Not All, of the Allegations Underlying the Claims InvolveSexual Harassment.
The primary issue on appeal was whether the EFAA applies to a case where some, but not all, of a plaintiff’s allegations underlying the claims involve sexual harassment. The division determined, yes, “the EFAA applies to an entire case, rather than to individual claims, provided the claims are ‘relate[d] to’ allegations of sexual harassment.”
The division found the reasoning of Johnson v. Everyrealm, Inc., 657 F. Supp. 3d 535 (S.D.N.Y. 2023), and Olivieri v. Stifel, Nicolaus & Co., 112 F.4th 74 (2d Cir. 2024), persuasive. Johnson held that the EFAA’s reference to “a case” in 9 U.S.C. § 402(a) “captures the legal proceeding as an undivided whole” and “does not differentiate among causes of action within it.” The division agreed, holding that under the EFAA, “a case” “encompasses all of the claims brought in a single action rather than individual allegations or claims.”
Plaintiff’s post-filing termination allegations were “related to” her sexual harassment claims because she alleged her termination was based, at least in part, on having filed the sexual harassment lawsuit.
The division distinguished these facts from a different case where a wage-and-hour claim resting on an “entirely independent basis” was held outside the EFAA’s scope because it had “nothing to do with the alleged sexual harassment.” Here, Plaintiff expressly alleged her termination was based in part on filing the sexual harassment lawsuit, linking those claims to the underlying harassment dispute.
2. Acknowledged but Undefined “Outer Limit” of Relatedness
The division acknowledged that there may be some “outer limit” at which a claim becomes so attenuated from the sexual harassment allegations that it falls outside the EFAA’s “related to” requirement. However, the division concluded that boundary “was not approached—much less crossed” on these facts and therefore declined to define it.
3. Rule 12(b)(1) Procedural Standard
The employer argued the district court erred by applying the Rule 12(b)(5) “failure to state a claim” standard (accepting allegations as true and viewing them in the light most favorable to the plaintiff) rather than the Rule 12(b)(1) subject-matter-jurisdiction standard, and that disputed facts regarding the arbitrability of plaintiff’s claims required an evidentiary hearing. The division found no reversible error: the employer never requested an evidentiary hearing below, never identified specific disputed facts through affidavits, deposition testimony, or other evidence, and attached only the arbitration agreement and the plaintiff’s sworn discrimination charge, which supported the plaintiff’s position.
Because no genuinely disputed jurisdictional facts existed, the district court was entitled to accept the complaint’s well-pleaded facts as true and rule without a hearing. The division held that arguments of counsel alone do not create a factual dispute.
Practical Implications
This ruling is the first published appellate opinion in Colorado to interpret the scope of the EFAA. Under the division’s holding, the EFAA applies to “a case” “relates to . . . the sexual harassment dispute.” 9 U.S.C. § 402(a). And a claim of retaliation that is based at least in part on the assertion of a claim of sexual harassment is “relate[d] to” a sexual harassment dispute sufficient for the EFAA to apply, even if the claim is also based on other allegations that do not involve sexual harassment. Therefore, an otherwise valid arbitration clause is not enforceable against a claim based on multiple factual allegations if one of the allegations relates to sexual harassment.
Retaliation and termination claims arising after a sexual harassment lawsuit is filed are particularly likely to be treated as “related to” the underlying dispute and therefore also exempt from arbitration, even if the retaliation is also nominally tied to a separate investigation (here, a wage-theft investigation).
There may be an outer limit where an unrelated claim is genuinely independent of the sexual harassment allegations (e.g., where a wage-and-hour claim arising from an entirely separate factual basis was sent to arbitration), but Colorado courts have not yet defined precisely where the line falls. Parties seeking to enforce an arbitration provision should expect a fact-intensive, case-by-case inquiry into “relatedness” going forward.
In the employment context, employers should consult with their lawyers about the potential benefits and drawbacks of requiring employees to sign arbitration agreements and whether the employers’ goals can be achieved through alternate approaches.
The division of the Court of Appeals affirmed the district court’s order denying the motion to dismiss and compel arbitration.
The opinion was authored by Judge Schutz, with Judges Lipinsky and Yun concurring.
Under the Mining Law of 1872 (the “Mining Law”)[2] lode claimants may, in certain circumstances, follow a vein’s downward course beneath neighboring claims.[3] This is known as the “Apex Rule” (herein, the “Rule”) and the rights it bestows upon a claimant are powerful since it (i) entitles miners to extract minerals that stray onto adjoining claims or other public land (and in some cases onto patented mining claims) that the miner does not own and (ii) provides a potential avenue to invalidate a rival claimant’s adjoining locations. However, the Rule’s applicability is also very narrow since many currently exploited and newly discovered deposits are widely diffused and lack an apex, and proving that extralateral rights exist—or have been violated—is a highly fact-dependent and technical exercise, making it costly to litigate disputes arising under the Rule.
What are Extralateral Rights and the Apex Rule?
At its most basic, the Apex Rule provides the holder of a valid lode claim with “extralateral rights” if the uppermost edge or point of the mineral vein (known as the “apex”) is located within his claim (whether at or below the surface). These extralateral rights then generally permit the miner to follow the vein onto all mining lands, whether unpatented or patented (including land previously located by others under the Mining Law) outside of his claim’s borders.[4] These extralateral rights are “purely statutory”—there is no supporting common law—and may also be referred to as the “right of lateral pursuit.”[5]
Establishing Extralateral Rights
The party claiming extralateral rights has the burden of proof to establish certain required elements, which typically requires having or developing extensive geological information about the claim(s) from which the claiming party argues the extralateral rights flow, as well as with respect to the adjacent claims:
Valid Lode Location: The claim must be a properly located lode mining claim (extralateral rights do not attach to placer, mill site, or tunnel site claims), patented or unpatented.[6]
Apex Within Claim Boundaries: The vein must have an apex that lies within the claim. While limited “legal/judicial apex” doctrines exist, they provide limited exceptions to this requirement.[7]
Downward Course (Dip) Into Certain Categories of Adjacent Lands: The vein must dip downward from the apex (i.e., there are no extralateral rights in a horizontal vein because it has no downward course) into land not previously appropriated or patented as non-mining land and not conflict with a prior apex right.[8]
Continuity of Vein: The vein must be continuous between the apex and the portion of the vein being pursued extralaterally; since veins frequently twist and turn, continuity can be difficult to prove without detailed mapping, drilling, expert analysis, and sometimes workings along the vein.[9]
Parallel End Lines: Since a vein cannot be pursued on its strike beyond the ends of its location (i.e., it can only be pursued beyond the side lines—not the end lines, see Diagrams 1 and 2 below), generally, the claim must have parallel end lines defining the lateral limits of the extralateral right; courts may recharacterize lines for the discovery vein, but parallelism still governs.[10]
The Practical Limits of the Apex Rule
Surface Use Not Included. Extralateral rights do not authorize entry on a neighboring property; any underground pursuit of the vein must originate from workings within your own surface estate or be obtained by separate access rights under applicable state law.[11]
Geological Realities Can Be Limiting. Because the extent of a claimant’s right to exercise his extralateral rights is limited to the length of the apex that lies within his claim, factors such as the location of the vein within the location, the length of the apex, and the point of entry and exit of the vein within the location can operate to limit a claimant’s extralateral rights.[12]
Deposit Type Matters. “Blanket veins” or broadly horizontal mineralized zones typically do not have a qualifying apex and therefore do not support extralateral rights.[13]
Modern Mining Realities. The Mining Law was enacted at a time when the only known method of locating lode deposits was by surface, visual geological observation. Because early miners did not recognize at that time that veins could be susceptible to folding or faulting or that several apexes might represent one vein, it was logical that surface discoveries would form the basis for locating claims. Notably, the United States is the only mining jurisdiction that still adheres to the rule and modern courts and commentators have questioned the rule’s fit with geological reality as now understood as well as modern mining methods.[14]
High Burden / Lack of Modern Precedent. The burden of proof on establishing extralateral rights (and the extent thereof) lies with the extralateral claimant. Courts have not established a uniform evidentiary standard, but the burden is typically “substantial”—requiring things such as geological mapping, expert opinion, and drilling results. Further, Apex Rule litigation has been very uncommon since the first part of the 21st century as modern operators instead frequently seek to avoid such costly, fact-intensive, and uncertain litigation by negotiating joint development or boundary agreements or purchasing adjacent claims.[15]
Competitive Positioning and Inter-Claim Conflict Considerations
The Role of Seniority. The exercise of extralateral rights does not depend upon seniority. However, when two or more veins intersect, the senior locator takes the ore within the space of intersection, while junior claimants retain rights to their claim and a right of way for convenient working. And when two veins unite, the older or prior location takes the combined vein below the point of union, including all forks and splits below that junction.[16]
Challenging Junior Locations. Historic Interior Department decisions support arguments that a junior claimant’s location based solely on a vein already validly appropriated (i.e., based on a vein whose apex lies within a senior locator’s claim) may be invalid for lack of discovery. While context-specific, this line of authority remains cited.[17]
Action Items for Claimants Seeking to Exercise Extralateral Rights
Assess the Deposit. Confirm whether your mineralization is a true lode or vein with an apex (versus a blanket-style deposit), which is often dispositive for extralateral analysis.
Map the Apex and End Lines with Precision. Delineate the apex’s location, length, width, and the claim’s end-line geometry to understand the true scope of any extralateral right.
Build the Geological Record. Collect geologic evidence to support vein type, continuity, and path (e.g., geologic mapping, oriented drilling, structural interpretation).
Plan Access. If extralateral pursuit is feasible, secure underground access from your surface estate or obtain easements/rights-of-way under state law.
Consider Commercial Solutions. Given the cost, uncertainty, and fact intensity involved in an Apex Rule dispute, consider mitigating risk through boundary agreements, joint development agreements, or strategic acquisitions instead of litigation.
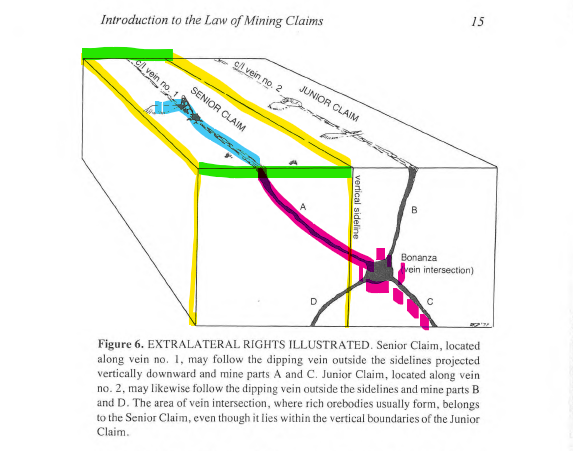
Diagram 1: Side Lines, End Lines, the Apex, the Dip, and “Lateral Pursuit”[18]
DIAGRAM KEY:
The side lines of a claim (yellow highlight) cannot exceed 1500 feet. In an ideal location, the side line should parallel the vein as closely as possible to maximize the extent of the lode included within the boundaries of a claim.
The end lines (green highlight) of a claim cannot exceed 600 feet. Extralateral rights do not extend beyond the end lines.
The “apex” of a vein, lode, or ledge is the top or highest point of the vein proper, whether at or below the surface and the terminal edge from which the vein extends downward to form a dip (blue highlight).
Extralateral rights, or the “right to lateral pursuit” entitle a senior claimant to follow the dipping vein (pink highlight). The area of vein intersection or “bonanza” belongs to the senior claimant, and he may continue to follow the vein originating at his apex beyond the intersection (dotted pink) to the maximum length permitted.
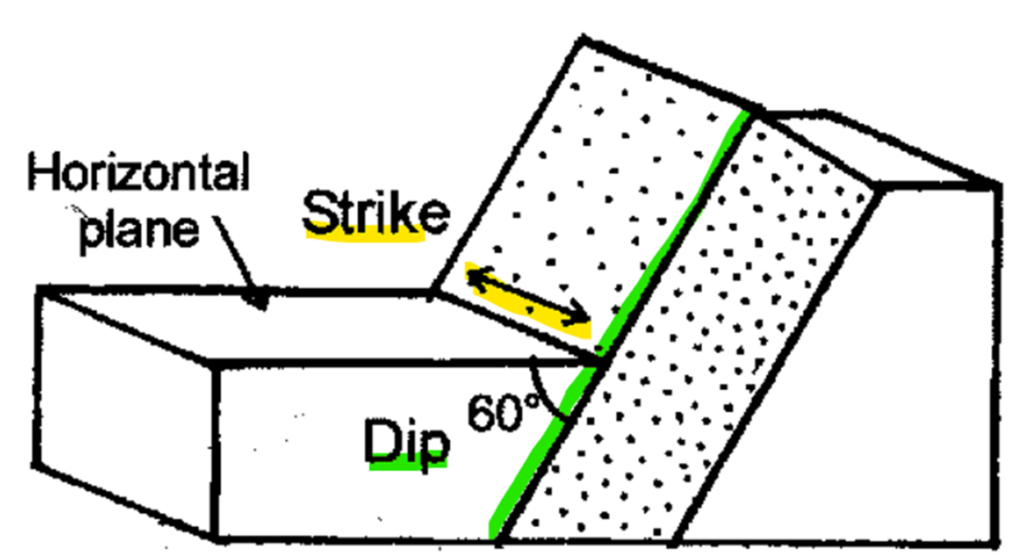
The “strike” of a vein is its horizontal course (yellow highlight).
The “dip” is the downward course of the vein at a right angle to the strike (green highlight).
[1] As indicated by the footnotes that follow, we have relied heavily on the American Law of Mining, published jointly by the Foundation for Natural Resources Law and Matthew Bender—an invaluable resource for information on the Mining Law of 1872—for this analysis.
[3] Am. Law of Mining, 2d Ed. § 37.01[1]; Silver Surprize v. Sunshine Mining Co., 15 Wash. App. 1, 6, 547 P.2d 1240, 1244 (1976).
[4]See 30 U.S.C. § 26 (providing that a lode locator “shall have the exclusive right of possession and enjoyment of all veins, lodes, and ledges throughout their entire depth, the top or apex of which lies inside of such surface lines extended downward vertically, although such veins . . . may so far depart from a perpendicular in their course downward as to extend outside the vertical side lines of such surface locations.”); supra, note 2, §§ 37.02[5], 37.05[1].
[11]See 30 U.S.C. § 26 (Nothing in this section shall authorize the locator or possessor of a vein or lode which extends in its downward course beyond the vertical lines of his claim to enter upon the surface of a claim owned or possessed by another); supra, note 2, § 37.01[3].
[13]Supra, note 2, § 37.01[4]. As noted in the introduction, the Apex Rule would not apply to a number of currently mined and recently discovered deposits, including in-situ uranium, lithium brine, and diffuse gold and silver, because these are broadly mineralized rather than vein- or lode-style deposits. Further, even if a mineral deposit meets the definition of a “vein” or “lode” under 30 U.S.C. § 26 (i.e., a mineral body within defined boundaries), it may not have an apex, in which case extralateral rights do not attach.
[14] Robert Leclerc, Perspectives Du Nord: A Canadian View of Problems and Opportunities in International Business Transactions, 32 Rocky Mtn. Min. L. Inst. 6 (1986), 6-6; Harry Macdonell, Comparative Analysis of American and Canadian Hard Mineral Laws, 10 Rocky Mtn. Min. L. Inst. 13 (1965), 439; Silver Surprize, 15 Wash. App. at 16, 547 P.2d at 1250 (“Modern mining practice seems to require amendment of the act of 1872 to deal specifically with the problems that arise from deep underground discoveries.”).
[17] M-36955, “Apex and Extralateral Rights Issues Raised by the Stillwater Mineral Patent,” 93 Interior Dec. 369, 382, 1986 I.D. LEXIS 34, *34; Bunker Hill & Co. v. Shoshone Mining Co., 1904 I.D. LEXIS 157, *9, 1904 I.D. LEXIS 157 (1904); Golden Link Mining, Leasing & Bonding Co., 1899 I.D. LEXIS 78, *5, 1899 I.D. LEXIS 78 (1899).
[18] Diagram taken from the Digest of Mining Claim Laws (Fifth Edition, 1996), published by the Rocky Mountain Mineral Law Foundation (now known as the Foundation for Natural Resources and Energy Law).
[19] Diagram taken from Research Gate, https://www.researchgate.net/figure/Diagram-illustrating-strike-and-dip-After-you-cross-the-bridge-walk-east-to-your-left_fig10_239604084.
On July 9, 2026, the Colorado Court of Appeals issued its opinion in Elk Creek Ranch Owners Association v. Elk Creek Ranch Development, Inc. and YZ Ranch, LLC, 2026 COA 58, addressing three issues: (1) when a postjudgment order denying one party’s attorney fee request becomes final and appealable in a multi-party case where other fee requests remain pending; (2) whether a breach of the implied duty of good faith and fair dealing constitutes a “default” triggering an attorney’s fees clause in a commercial lease; and (3) the proper methodology for calculating attorney fee awards under the lodestar method. The division reversed the district court’s denial of the Association’s fee request against YZ Ranch, reversed the fee award to ECRD, and remanded with directions.
Background
This case arises from a dispute concerning Elk Creek Ranch, a residential development in Rio Blanco County, Colorado. Elk Creek Ranch Development, Inc. (“ECRD”) developed the property and created its homeowners’ association, Elk Creek Ranch Owners Association (the “Association”). ECRD also formed a separate entity, ECO, to serve as the Association management company. Meanwhile, YZ Ranch, LLC, the owner of property adjacent to Elk Creek entered a lease (the “Lease”) with ECO as tenant that granted fishing access along Elk Creek to the Association’s members.
The Association brought suit against YZ Ranch for breaching the implied duty of good faith and fair dealing under the Lease, against ECO for breaching its management agreement with the Association (the “Management Agreement”), and against ERCD for violating the protective covenants that govern the development (the “Covenants”). At the close of evidence, the court dismissed the Association’s claims against ERCD on statute of limitations grounds. The remaining claims went to trial, where the jury found in the Association’s favor against YZ Ranch and ECO.
Following trial, the parties filed multiple requests for postjudgment attorney fees. The Association sought fees from YZ Ranch under the Lease and from ECO under the Management Agreement; as for ECRD, it sought fees from the Association under the Covenants. On August 20, 2024, the district court denied the Association’s fee request against YZ Ranch—concluding that under the plain language of the Lease, YZ Ranch, as landlord, could never trigger the fee-shifting clause—while simultaneously granting the Association’s fee request against ECO and granting ECRD’s fee request against the Association. The granted fee requests were not reduced to sums certain until a subsequent order entered on April 4, 2025. The Association filed its notice of appeal on May 21, 2025.
The Division’s Analysis
Appellate Jurisdiction and Finality. As a threshold matter, the division addressed whether the Association’s notice of appeal was timely under C.A.R. 4(a), given that it was filed more than 49 days after the August 20, 2024 order denying its fee request against YZ Ranch. The division applied the two-part finality test from Luster v. Brinkman, 250 P.3d 664 (Colo. App. 2010), asking (1) whether the order completely resolved the rights of the parties as to the particular part of the action in which it was entered, and (2) whether the order was more than merely ministerial. The division concluded that because other parties’ fee requests remained pending and had not yet been reduced to sums certain, the August 2024 order did not finally resolve all fee-related matters. Relying on persuasive federal authority—Mayer v. Wall Street Equity Group, Inc., 672 F.3d 1222 (11th Cir. 2012), and In re Syngenta AG MIR 162 Corn Litigation, 61 F.4th 1126 (10th Cir. 2023)—the division held that piecemeal appeals of fee orders should be avoided when other fee requests in the same action remain outstanding. Accordingly, the final appealable order was the April 4, 2025 order reducing the granted fee awards to sums certain, making the Association’s May 21, 2025 notice of appeal timely under C.A.R. 4(a).
Fee-Shifting Under the Terms of the Lease. On the merits, the division reversed the district court’s denial of the Association’s attorney fee request against YZ Ranch. Section 11.15 of the Lease provided for attorney’s fees upon “a default on the part of either party in the performance of any of the terms and conditions of this Lease.” The district court had read the undefined, lowercase term “default” as coextensive with the defined term “Default” in Section 8.1—which referred only to a “Default by Tenant” (e.g., failure to pay rent)—and thus concluded that YZ Ranch, as landlord, could never trigger the fee clause.
The division disagreed, holding instead that an undefined term in a contract must be given its plain and ordinary meaning and is not interchangeable with terms that the same instrument defines elsewhere. Applying the plain-meaning definition of “default,” the division held that any breach of contract constitutes a “default” under Section 11.15. The division further held that because a breach of the implied duty of good faith and fair dealing is itself a breach of contract—not a separate tort or independent cause of action—the jury’s finding that YZ Ranch breached the implied duty of good faith and fair dealing under the Lease entitled the Association to reasonable attorney’s fees and costs from YZ Ranch under Section 11.15.
Attorney Fee Award Methodology. Finally, the division reversed the district court’s award of $1,261,649.10 in attorneys’ fees to ECRD under the Covenants. The district court found, and the division affirmed, that ERCD’s fee request was unreasonable because the matter was overstaffed and ERCD failed to isolate the fees it actually incurred from those incurred by YZ Ranch and ECO, parties that shared the same counsel. But rather than excluding these unreasonable hours before calculating the lodestar, the district court calculated the full lodestar first and then applied a flat twenty-five percent reduction.
The division held this was backwards under Payan v. Nash Finch Co., 2012 COA 135M. Under Payan and Hensley v. Eckerhart, 461 U.S. 424 (1983), the US Supreme Court instructed that to calculate the lodestar, courts must first determine the “reasonable number of hours expended by counsel” on the case by excluding the “excessive, redundant, or otherwise unnecessary” hours and then multiply these reasonable hours by the reasonable hourly rate. Applying Payan, the division reasoned that an across-the-board percentage reduction after calculating the lodestar, like the district court applied here, inverts the proper methodology and constitutes reversible error.
Significance
This opinion offers several practical takeaways for Colorado practitioners. First, on appellate jurisdiction, the division’s holding establishes that in cases with requests for postjudgment attorney fees from multiple parties, a denial of one request is not final and appealable until all requests have been resolved and reduced to sums certain. Second, the decision underscores the importance of precise drafting in fee-shifting clauses. The division’s distinction between the undefined, lowercase term “default” and the specifically defined, capitalized term “Default” reinforces that courts will not conflate defined and undefined terms. Third, the division’s holding clarifies that a successful good-faith-and-fair-dealing breach can independently support an attorney fee award depending on the plain language of the contract’s fee-shifting clause. Fourth, the division’s treatment of the lodestar methodology reaffirms that courts must exclude unreasonable, excessive, and redundant hours before calculating the lodestar, not after. Courts may not shortcut the analysis by applying a blanket percentage reduction to a lodestar calculated from unfiltered hours.
SEC SEEKS PUBLIC COMMENT ON NOVEL EXCHANGE-TRADED FUNDS
On June 30, the U.S. Securities and Exchange Commission’s (“SEC” or “Commission”) issued a request for public comment (the “Request for Comment”) from funds, their advisers, investors and other market participants on exchange-traded funds (“ETFs”) seeking to invest in innovative asset classes or engage in novel investment strategies (“Novel ETFs”). The Request for Comment specifically seeks comments on ways to facilitate innovation in ETFs while still protecting investors, maintaining fair, orderly, and efficient markets, and facilitating capital formation.
The Request for Comment noted that ETF sponsors have expressed interest in providing exposure markets, and facilitating capital formation, including crypto assets; commodity-focused instruments; single‑stock strategies; heightened leverage; blockchain-enabled opportunities; private assets; event contracts; and/or a combination of the aforementioned categories. The Request for Comment outlined questions that have been raised by market participants regarding Novel ETFs (for example, whether a Novel ETF would qualify as an “investment company” or operate pursuant to the requirements of Rule 6c-11 under the Investment Company Act of 1940 (the “1940 Act”).
Under Section 3 of the 1940 Act, “investment company” is defined as an issuer that (i) is or holds itself out as being engaged primarily , or proposes to engage primarily in the business of investing, reinvesting, or trading in securities (the “Subjective Test”), or (ii) is engaged or proposes to engage in the business of investing, reinvesting, owning, holding, or trading in securities, and owns or proposes to acquire investment securities having a value exceeding 40% or more of such issuer’s total assets (exclusive of Government securities and cash items), on an unconsolidated basis. Among other questions, the Request for Comment asks whether a Novel ETF would meet the Subjective Test even if its principal investment strategy is to invest in securities that may not be securities.
With respect to Rule 6c-11 under the 1940 Act, the Request for Comment includes, for example, questions regarding portfolio-related conditions, including (i) whether the assets of Novel ETFs present any questions regarding the functioning of the ETF arbitrage mechanism and the supporting secondary trading activity, investor protection, the maintenance of fair, orderly, and efficient markets, or other structural or operational issues, and (ii) whether Rule 6c-11 should be amended to address these or other questions related to Novel ETFs.
Among other items, the Request for Comment also includes questions regarding automatic effectiveness of post-effective amendments filed pursuant to Rule 485 under the Securities Act of 1933, including whether the 75-day and 60-day automatic effectiveness periods should be extended for Novel ETFs.
Comments must be submitted to the Commission by August 31.
SUPREME COURT UNANIMOUSLY UPHOLDS THE SEC’S ABILITY TO USE “DISGORGEMENT” IN SRIPETCH V. SEC
On June 4, the United States Supreme Court (the “Court”) issued a unanimous decision in Sripetch v. Securities and Exchange Commission, No. 25-466, addressing what the SEC must show to obtain disgorgement from a defendant in federal court. The Supreme Court held that the SEC need not prove investor pecuniary loss to obtain disgorgement under the Securities Exchange Act of 1934, as amended (the “Exchange Act”), so long as the remedy is directed to the defendant’s unjust gains and otherwise fits within the equitable framework assumed by the Court for purposes of the case. In doing so, the Court also resolved a circuit split: the First and Ninth Circuits did not require proof of investor pecuniary loss, while the Second Circuit did.
Sripetch arose against the backdrop of the SEC’s evolving authority to seek monetary remedies in federal securities enforcement actions. As explained in the Supreme Court’s decision, when Congress created the SEC in the 1930s, the SEC’s statutory enforcement toolkit did not include monetary awards and was limited principally to seeking injunctions against future violations of the federal securities laws. Congress later expanded the agency’s enforcement powers, including by authorizing monetary penalties in 1990. Beginning in the 1970s, however, courts began permitting the SEC to seek disgorgement as ancillary equitable relief in enforcement actions. In 2002, Congress enacted the Sarbanes-Oxley Act, which, among other things, provides that the SEC may seek “equitable relief” for the “benefit of investors” in civil actions under Section 21(d)(5) of the Exchange Act.
Over time, the SEC’s disgorgement practice became a significant enforcement remedy and, in some cases, produced awards that were deposited with the United States Treasury or exceeded the defendant’s own profits from the alleged violation. The Supreme Court previously addressed aspects of that practice by applying a five-year statute of limitations in Kokesh v. SEC, 581 U. S. 455 (2017), and by imposing two “traditional equitable principles” limits on its use: (1) remedies are limited to a defendant’s net profits, and (2) the award must go to victims rather than be imposed as a penalty where feasible, Liu v. SEC, 591 U.S. 71 (2020).
After Liu, Congress amended the Exchange Act in a way that made the SEC’s disgorgement authority more explicit but also generated new questions about the relationship between statutory disgorgement and equitable limits. Congress left intact Exchange Act Section 21(d)(5), which authorizes “equitable relief,” and added Section 21(d)(7), which expressly authorizes the SEC to seek disgorgement in enforcement proceedings. Congress also provided that federal district courts may require disgorgement of “any unjust enrichment” received as a result of a securities-law violation and added limitations provisions addressing both equitable relief and disgorgement. Unlike Section 21(d)(5), Section 21(d)(7) does not contain language requiring relief to be “for the benefit of investors,” which led to differing views about how Liu’s requirements apply after the statutory amendments and created the conflict that prompted Supreme Court review. The Second Circuit held that the disgorgement remedy under both Sections 21(d)(5) and 21(d)(7) is equitable and available only if it can be awarded to victims, which the court defined as those who have suffered “pecuniary harm.” In contrast, the First Circuit held that, because disgorgement’s purpose is to deprive wrongdoers of ill-gotten gains, a pecuniary harm showing is not required.
In Sripetch, the underlying dispute stemmed from a civil enforcement action against Ongkaruck Sripetch (“Sripetch”) and other defendants in the United States District Court for the Southern District of California, in which the SEC alleged securities-law violations arising from alleged classic “pump and dump” schemes involving at least 20 penny-stock companies. The SEC charged Sripetch with six counts of securities fraud and one count of selling unregistered securities, and it sought, among other remedies, disgorgement of more than $6.6 million in ill-gotten gains. Sripetch ultimately consented to entry of judgment and agreed that the District Court could order disgorgement, but when the SEC sought more than $4.1 million in disgorgement, Sripetch objected that the request was inconsistent with Liu v. SEC because the SEC had not shown that investors suffered financial losses and therefore had not identified “victims” for whom disgorgement could be awarded. The SEC responded that investors may qualify as victims even without proof of pecuniary loss and, in the alternative, that its evidence showed investor pecuniary harm in any event. The District Court for the Southern District of California accepted the SEC’s alternative evidentiary position, concluded that the SEC had made an adequate showing of pecuniary harm, and ordered disgorgement of $2,251,923.16 in net profits plus prejudgment interest without deciding whether such a showing was legally required.
On appeal, Sripetch again argued that disgorgement under Exchange Act Sections 21(d)(5) and 21(d)(7) requires proof that investors suffered pecuniary harm. The Ninth Circuit ruled against Sripetch, concluding that demonstrating pecuniary loss to investors is unnecessary to support a disgorgement order. The Ninth Circuit acknowledged Liu’s requirement that disgorgement be awarded for victims but rejected the argument that “victim” status turns on proof of measurable financial loss. In doing so, the Ninth Circuit aligned with the First Circuit and rejected the Second Circuit’s approach. The Supreme Court granted certiorari to decide the narrow question whether the SEC must prove that investors suffered pecuniary loss before obtaining disgorgement under Section 21(d)(5) or Section 21(d)(7) of the Exchange Act.
In a unanimous opinion by Justice Gorsuch, the Court affirmed the Ninth Circuit, holding that the SEC does not need to show financial harm to investors. The Court explained that traditional equitable principles do not require proof of pecuniary loss and that a person whose legally protected interests have been invaded may qualify as a victim for disgorgement purposes even without a measurable financial loss. Accordingly, the Supreme Court rejected Sripetch’s reading of Liu v. SEC because Liu required disgorgement to be “awarded for victims,” but did not make pecuniary loss a prerequisite to victim status. The Court also rejected Sripetch’s “status quo” argument, reasoning that, where a defendant is unjustly enriched without leaving the victim financially worse off, equity traditionally favors stripping the wrongdoer’s gain rather than allowing the wrongdoer to retain the benefit.
The Supreme Court’s decision in Sripetch further distinguished SEC enforcement actions from private securities-fraud suits, which do require a preliminary showing of the plaintiff’s economic loss. The Court, however, did not decide the full scope of the SEC’s post-Liu disgorgement authority, including whether Congress’s addition of Section 21(d)(7) displaced any traditional equitable limits on disgorgement. Justice Thomas concurred, agreeing with the result while stating that a future case should address whether SEC disgorgement under the amended Exchange Act is a legal remedy that implicates the Seventh Amendment right to a jury trial.
SEC ANNOUNCES ENFORCEMENT RESULTS FOR FISCAL YEAR 2025
On April 6, the Commission announced enforcement results for its fiscal year ended September 30, 2025 (“FY 2025”). During FY 2025, the Commission filed 456 enforcement actions comprised of 303 standalone actions and 69 follow on administrative proceedings that sought to bar or suspend individuals from certain securities market functions based on criminal convictions, civil injunctions, or other orders. The Commission obtained orders for monetary relief of $17.9 billion.
The press release announcing the enforcement results (the “Press Release”) included that, “[t]hese enforcement actions addressing a broad range of misconduct demonstrate the Commission’s prioritization of cases that directly harm investors and the integrity of the U.S. securities markets, including offering frauds, market manipulation, insider trading, issuer disclosure violations, and breaches of fiduciary duty by investment advisers.” The Press Release also noted that FY 2025 was a transition period for the enforcement division, noting its renewed focus on bringing actions that prevent investor harm and that moving forward, enforcement priorities and results would be linked to the Commission’s core mandate and focus on (i) standing up to fraud and market participants engaged in such misconduct; (ii) addressing fraudulent and manipulative conduct through appropriate remediation; and (iii) repaying investor losses when harmed.
SUPREME COURT DECISION IN FS CREDIT OPPORTUNITIES CORP. V. SABA
On June 11, the United States Supreme Court held in FS Credit Opportunities Corp. v. Saba Capital Master Fund, Ltd., No. 24-345, that Section 47(b) of the 1940 Act does not impliedly allow private parties to sue for rescission of contracts that allegedly violate the 1940 Act. The 6–3 decision reverses the prior decision by the Second Circuit and resolves a longstanding circuit split.
Section 47(b) of the 1940 Act permits rescission of any contract that allegedly violates the 1940 Act as a remedy to parties to such a contract, provided that rescission would not produce a more inequitable result than performance. In recent years, litigants have argued that Section 47(b) implicitly creates a private right of action for rescission available not just to parties to the contract, but to any investor affected by it.
The case arose from a dispute between investment companies that manage closed-end mutual funds (the “Funds”) and Saba Capital Master Fund, Ltd., and Saba Capital Management, L.P. (collectively, “Saba”), each an activist investor. The Funds were incorporated in Maryland and adopted resolutions opting into the Maryland Control Share Acquisition Act, which limits the voting rights of shareholders holding a disproportionate number of shares—such as activist investors—unless other shareholders approve. Saba sued the Funds, arguing that these resolutions violate the 1940 Act’s requirement that every share of stock be a voting stock with equal voting rights. Saba’s argument relied on Section 47(b), which provides that “a court may not deny rescission” of contracts violating the 1940 Act “at the instance of any party” unless certain equitable conditions are met.
The Court’s reasoning focused on several arguments, including the following:
The Court concluded that Section 47(b)’s language stating “a court may not deny rescission at the instance of any party” is a directive to courts, not a grant of rights to individuals. This language assumes that parties are already before the court and merely directs how courts should exercise their remedial authority; it does not confer a standalone right to sue.
The Court noted that under longstanding contract-law principles, rescission is a remedy, not a cause of action in and of itself.
The Court observed that Congress created two express private rights of action elsewhere in the 1940 Act—for breach of fiduciary duty by investment advisers and for recovery of certain short-term profits. The existence of these express provisions demonstrates that when Congress wants to provide a private remedy, it does so expressly.
Saba relied heavily on the Court’s 1979 decision in Transamerica Mortgage Advisors, Inc. v. Lewis (“TAMA”), which found an implied right of action in a comparable “shall be void” provision of the Investment Advisers Act of 1940 (“Advisers Act”). However, the Court noted that Congress amended Section 47(b) in 1980 to delete the “shall be void” language on which TAMA relied and replaced it with language focused on a court’s remedial authority. In contrast, Congress retained “shall be void” language in other related provisions, suggesting the change was intentional and substantive rather than merely clarifying.
The Court’s decision significantly narrows the ability of private parties (including activist investors) to bring implied private suits under the 1940 Act to challenge fund governance decisions. The decision also reinforces the principle that the SEC, as the 1940 Act’s primary enforcer, is the principal avenue for addressing alleged 1940 Act violations, and private enforcement must be grounded in an express statutory grant.
SEC PUBLISHES DRAFT STRATEGIC PLAN FOR FY 2026-2030
On June 2, the SEC published its Draft Strategic Plan (the “Draft Strategic Plan”) for Fiscal Years 2026-2030 and opened the plan for public comment through July 2, 2026. The Draft Strategic Plan provides a roadmap for the agency’s direction and the initiatives SEC Chairman Paul Atkins intends to advance.
The Draft Strategic Plan indicates that the SEC is focusing on three primary goals as part of its strategy over the next four years:
Goal 1: Modernize regulation. The SEC plans to update its regulatory approach to better support innovation, capital formation, market efficiency, and investor protection, including by addressing digital assets, distributed ledger technology, and alternative trading platforms. In particular, the Draft Strategic Plan emphasizes easier access to public and private capital markets, modernized early-stage fundraising rules, streamlined disclosure, updated shelf registration, and improvements to Regulation A for smaller issuers.
Goal 2: Change regulatory practices. The SEC plans to increase engagement with stakeholders, make compliance easier for market participants, and shift enforcement back toward clear violations of established law, especially fraud and manipulation. The Draft Strategic Plan specifically identifies possible retrospective review of rules involving foreign private issuers, quarterly and private fund reporting, executive compensation, alternative trading systems, and market structure.
Goal 3: Improve internal operations. The SEC plans to reorganize, modernize technology, improve performance management, and use internal reporting to track accountability, resource use, and program success.
The Draft Strategic Plan indicates that the SEC seeks to regulate in a way that is more innovation-friendly, more predictable for market participants, more focused on fraud and manipulation, and more efficient internally.
Compared with the strategic plan adopted under former Chairman Gary Gensler for Fiscal Years 2022-2026, the Draft Strategic Plan retains the same mission statement, and both plans emphasize technology, data, and the need to keep pace with changing markets. Under SEC Chairman Paul Atkins’ Draft Strategic Plan, however, the order of priorities has shifted. For instance, the SEC’s plan for Fiscal Years 2022-2026 emphasized keeping pace with emerging risks through enforcement measures. By contrast, the Draft Strategic Plan states that enforcement should focus on established legal violations and should not be used as a substitute for policymaking. Accordingly, the plan signals a likely push toward clearer, more formal rules rather than regulation primarily through enforcement.
Going forward, market participants should watch for the final Strategic Plan, along with any additional SEC rulemaking or guidance, to evaluate how these activities correspond with the SEC’s stated strategic priorities in the draft Strategic Plan.
SEC RESCINDS POLICY REGARDING DENIALS OF SETTLEMENTS IN ENFORCEMENT ACTIONS
Historically, pursuant to Rule 202.5(e) of the SEC’s informal rules of procedure, defendants or respondents settling enforcement actions were required to agree not to publicly deny the allegations made in an SEC complaint or administrative order. On May 18, the SEC rescinded this informal rule. As a result, defendants settling SEC enforcement actions are no longer required to comply with no-deny restrictions as a condition of settlement. Such defendants will now be able to freely comment on and contest such allegations made in enforcement actions.
The SEC gave four reasons for the rescission of the informal rule:
The Commission noted that it is not aware of any instance in which an action was reopened following a violation of the no-deny provision.
Given the prevalence of social media, implementation of the rule has become more difficult and the line between public and private statements has become less clear.
Rescinding this rule aligns the SEC with the majority of federal agencies that do not have a similar rule.
Rescinding the rule gives the Commission additional flexibility in settling enforcement actions. The SEC noted that the rule will no longer “preclude settlements with defendants who do not wish to waive their rights by signing a no-deny provision that imposes a contractual obligation regarding denials that continues into the future beyond the time of settlement.”
Going forward, the SEC has stated that it will no longer enforce no-deny restrictions that have previously been agreed to in settlements.
UPCOMING CONFERENCES
2026
Date
Host*
Event
Location
7/21
MFDF
Director Discussion Series – Open Forum (Philadelphia)
Philadelphia, PA
7/21
MFDF
Board Oversight of Subadvisers: Compliance and Regulatory Issues
Webinar
7/28
MFDF
Director Discussion Series – Open Forum (NYC)
New York, NY
7/29
ICI/IDC
Cybersecurity in the Age of AI: A Primer for Fund Directors
Webinar
7/29
MFDF
Closed-End Fund Roundtable
New York, NY
9/1
MFDF
AI in the Fund Boardroom
Webinar
9/9
MFDF
Section 351 & ETF Formation: What Fund Directors Need to Know
Webinar
9/14
MFDF
Intermediary Fees: What Today’s Trends Mean for Independent Directors
Webinar
9/15-17
ICI/IDC
Compliance, Risk, and Legal Conference
Nashville, TN
9/17
MFDF
How the SPIVA U.S. Scorecard Understates the Performance of Actively Managed Mutual Funds – What Directors Should Know
Webinar
9/23
MFDF
Director Discussion Series – Open Forum
Denver, CO
9/27-30
ICI/IDC
Tax and Accounting Conference
Marco Island, FL
10/15
MFDF
In Focus – Board Oversight Approaches to AI and Risk Management
Webinar
10/21
MFDF
Director Discussion Series – Open Forum
Boston, MA
10/26-28
ICI/IDC
Fund Directors Conference
Scottsdale, AZ
11/10
ICI/IDC
2026 Retail Alternatives and Closed-End Funds Conference
New York, NY
11/2
MFDF
ETFs, Mutual Funds, and Taxes: A Structural Comparison for Fund Boards
Webinar
11/9
MFDF
In Focus – Usage of AI in the Boardroom
Virtual
12/2-3
ICI/IDC
Foundations for Fund Directors
Virtual
2027
Date
Host*
Event
Location
2/1
MFDF
2027 Directors’ Institute
Amelia Island, FL
2/3-5
ICI/IDC
ICI Innovate
Phoenix, AZ
3/14-17
ICI/IDC
Investment Management Conference
San Diego, CA
4/8
MFDF
2027 Fund Governance & Regulatory Insights Conference
Washington, DC
5/10-12
ICI/IDC
Leadership Summit
Washington, DC
5/10-12
ICI/IDC
Fund Directors Workshop (IDC)
Washington, DC
6/7-9
ICI/IDC
ETF Conference
New Orleans, LA
9/19-22
ICI/IDC
Tax and Accounting Conference
Phoenix, AZ
10/25-27
ICI/IDC
Fund Directors Conference
Scottsdale, AZ
11/9
ICI/IDC
Retail Alternatives and Closed-End Funds Conference
New York, NY
*Host Organization Key: Mutual Fund Directors Forum (“MFDF”), Independent Directors Council (“IDC”), and Investment Company Institute (“ICI”)
On June 11, 2026, the Colorado Court of Appeals held in Nunn v. Nestor, 2026 COA 49, that a verdict form labeled “Special Verdict Form” was in fact a general verdict accompanied by answers to interrogatories under Colorado Rule of Civil Procedure 49(b). The division reached this conclusion because the verdict form required the jury to decide the ultimate legal result of each claim, leaving nothing for the court to do but enter judgment. Because the form constituted a general verdict rather than a special verdict, the defendant-appellant was required to object to any inconsistency before the jury was discharged. His failure to do so resulted in waiver of the right to raise that challenge on appeal.
Background
In May 2021, Officer Nestor pulled over Nunn, a young black man, for failing to yield to an emergency vehicle. As Nunn handed Nestor his registration and reached for his wallet to produce his driver’s license, Nestor drew his gun and called for backup. Nunn got out of his car at gunpoint as more officers arrived. Once out of the car, Nunn was tackled to the ground by another officer, tased twice, arrested, and charged with several crimes. All charges were later dismissed.
Nunn sued Nestor for excessive force, unreasonable seizure, failure to intervene in another officer’s use of force, and an equal protection violation based on racial discrimination. The jury found in Nunn’s favor only on the excessive force claim based on the officer pointing his weapon at Nunn.
Nestor appealed, contending that the jury’s verdict was irreconcilably inconsistent. Nunn responded that Nestor failed to preserve that issue for appeal because he did not object before the jury was dismissed.
Both arguments turned on whether the jury’s verdict was (1) a special verdict, or (2) a general verdict with special interrogatories. A challenge to a special verdict need not be preserved before the jury is discharged, but a challenge to a general verdict with interrogatories must be raised before discharge or it is waived.
The Jury Verdict Form
The trial court submitted a verdict form to the jury labeled “SPECIAL VERDICT FORM-DEFENDANT NESTOR.” In relevant part, the verdict form asked:
SECTION I: PRESTON NUNN’S EXCESSIVE FORCE CLAIM AGAINST GABRIEL NESTOR
1. Did Defendant Gabriel Nestor deprive Plaintiff Preston Nunn of his constitutional right to be free from excessive force?
Yes X No
. . . .
(a). Did Defendant Gabriel Nestor deprive Plaintiff Preston Nunn of his constitutional right to be free from excessive force when he pointed his duty weapon at Plaintiff Nunn?
Yes X No
(b). Did Defendant Gabriel Nestor deprive Plaintiff Preston Nunn of his constitutional right to be free from excessive force when he used his Taser on Plaintiff Nunn?
Yes No X
. . . .
SECTION II: PRESTON NUNN’S UNREASONABLE SEIZURE CLAIM AGAINST GABRIEL NESTOR
1. Did Defendant Gabriel Nestor deprive Plaintiff Preston Nunn of his constitutional right to be free from unlawful seizure?
Yes No X
The Division’s Analysis
The Division began by highlighting that Colo. R. Civ. P. 49 is identical to Fed. R. Civ. P. 49, and that the Division may look to federal authority for guidance in construing the Colorado rule.
The division recognized that the Colorado Rules of Civil Procedure contemplate three types of verdicts and described each as follows:
General Verdict: A verdict by which the jury finds in favor of one party or the other, as opposed to resolving specific legal questions. The hallmark of a general verdict is that it requires the jury to announce the ultimate legal result of each claim and leaves nothing for the judge to do other than enter judgment.
Special Verdict: A verdict in which the jury makes findings only on factual issues submitted by the judge, and the judge decides the legal effect of those findings. It is a special verdict only if the judgment itself requires the judge to apply the law to the facts found by the jury.
General Verdict with Interrogatories: A verdict that combines a general verdict with factual questions that, standing alone, would be special verdicts. If the court asks for a general verdict, then any factual question is an interrogatory.
The division reaffirmed that if a party fails to object to a Rule 49(b) general verdict accompanied by answers to interrogatories before the jury is discharged, the party waives any later challenge based on an alleged inconsistency. A timely objection matters because it gives the trial court the option to send the jury back for further deliberations.
The division next examined the language of the verdict form, which was labeled as a “Special Verdict Form.” The form asked the jury:
“Did Defendant Nestor deprive Plaintiff Preston Nunn of his constitutional right to be free from excessive force?”
“Did Defendant Nestor deprive Plaintiff Preston Nunn of his constitutional right to be free from unlawful seizure?”
The division concluded that those questions required the jury to decide the ultimate legal result of each claim. By answering these questions, the jury left nothing for the court to do but enter judgment. All remaining factual questions were therefore interrogatories accompanying a general verdict under Rule 49(b).
The verdict form’s label as a “Special Verdict Form” did not change the conclusion because the label given to a verdict form is not controlling.
Accordingly, the division held Nestor needed to object to any inconsistencies before the jury was discharged to preserve the issue for appellate review. Because he didn’t object, Nestor was barred from raising his inconsistent-verdict argument on appeal.
Implications
In order to preserve its rights to appeal, a party should object to a plausible verdict-inconsistency issue before the jury is discharged. Waiting until post-trial motions or appeal risks waiver of the objection if the verdict is later characterized as a general verdict or a general verdict accompanied by answers to interrogatories.
In addition, parties should examine the verdict form’s language, not just the label. If the form requires the jury to determine liability or damages and leaves only entry of judgment for the court, the form may be treated as a general verdict even if it is labeled as a “Special Verdict Form.” The division’s decision also reinforces the importance of preserving objections in real time. This preserves the client’s right to challenge a verdict’s consistency on appeal.
This decision clarifies the boundaries between special verdicts and general verdicts (including general verdicts with interrogatories). The division’s reasoning reinforces that substance—not the form’s label—controls the classification.
The Court of Appeals affirmed.
The opinion was authored by Judge Moultrie, Judges Gomez and Berger concurring.
On June 25, 2026, the Colorado Court of Appeals issued its opinion in Wright v. Goldstein, 2026 COA 54, addressing whether a party waives its right to challenge arbitrability, on the ground that no agreement to arbitrate exists, by participating in an arbitration proceeding before objecting. The division held that, under the Colorado Revised Uniform Arbitration Act (“CRUAA”), § 13-22-223(1)(e), C.R.S. 2025, a party preserves the objection so long as it is raised to the arbitrator “not later than the beginning of the arbitration hearing.” In so holding, the division expressly declined to follow a prior division’s contrary conclusion in Harper Hofer & Associates, LLC v. Northwest Direct Marketing, Inc., 2014 COA 153, creating a split among divisions of the court.
Background
The CRUAA, §§ 13-22-201 to -230, C.R.S. 2025, provides a uniform framework for arbitration and strictly limits a reviewing court’s role, permitting a court to decline to confirm an award only for the reasons enumerated in § 13-22-223(1). The absence of an agreement to arbitrate is one such ground, but it is waivable. Under § 13-22-223(1)(e), a party waives the objection if it participates in the arbitration without raising it “not later than the beginning of the arbitration hearing.”
In 2012, James Wright and Daniel Goldstein, through their companies Damages Inc. and Altru-Media (a subsidiary of Page 1 Solutions), respectively, formed And Justice For All, LLC (“AJFA”), a legal-advertising website venture, with each company holding a fifty percent interest. They executed an operating agreement and a memorandum of understanding (“MOU”). The MOU contained a broad arbitration clause requiring disputes to be submitted to the American Arbitration Association (“AAA”) for binding arbitration.
AJFA was never profitable. In 2019, Goldstein moved to sell Page 1 Solutions’ assets. Believing this breached the operating agreement, the Wright plaintiffs sued the Goldstein defendants, asserting breach of contract and several tort claims. The Goldstein defendants moved to compel arbitration under the MOU. Over the Wright plaintiffs’ objection, the district court compelled arbitration.
During a pre-hearing conference almost a year into the arbitration proceeding, and just four days before the scheduled merits hearing, Wright objected that he signed the MOU only as a corporate representative of Damages Inc. and was therefore not personally bound by the arbitration clause. Accordingly, Wright argued the claims he was asserting in his individual capacity were not required to be arbitrated. The arbitrator, relying on Harper Hofer, found the objection waived because Wright had not also sought a judicial stay under § 13-22-207(2).
The arbitrator found the Goldstein defendants not liable on any claim and awarded them their attorneys’ fees. The Wright plaintiffs moved to vacate the award, but the district court instead confirmed it, agreeing with the arbitrator that Wright waived his arbitrability objection by failing to raise it earlier in a motion to stay the arbitration. The Wright plaintiffs appealed.
The Division’s Analysis
The court of appeals reversed, holding that the CRUAA’s plain language requires only that a party raise an objection to arbitral jurisdiction to the arbitrator no later than the beginning of the hearing, and it does not additionally require the objecting party to seek a judicial stay. The court found persuasive out-of-state authority construing similar statutory language and disagreed with Harper Hofer for failing to grapple with the statute’s plain text. The division emphasized that the General Assembly may modify ordinary waiver principles, and in fact did so here by setting a relatively late objection deadline that parties may not waive or vary under § 13-22-204(3)(a). The court remanded for the district court to determine arbitrability of the claims between Wright in his individual capacity and the Goldstein defendants.
On a separate issue, the court affirmed that Goldstein and Page 1 Solutions, though nonsignatories to the MOU, assumed the obligation to arbitrate through their conduct, including by actively and voluntarily participating in the proceeding, listing themselves as claimants, and declining to seek resolution of claims outside arbitration.
Significance
The decision creates a split among divisions of the Colorado Court of Appeals on the question of when a party must raise an objection to arbitrability to avoid waiving it under the CRUAA. Under Wright v. Goldstein, a party contesting the existence of an arbitration agreement need only object to the arbitrator before the hearing begins to preserve the issue for a later motion to vacate and is not required to seek a judicial stay. Harper Hofer, however, indicates a motion to stay is required under § 13-22-207(2) to preserve an objection to arbitrability.
The opinion was authored by Judge Sullivan, with Judges Pawar and Meirink concurring.
“Maria has long been an important contributor to the firm’s clean energy and renewable energy work,” said Zachary D. Detra, Head of the firm’s Transactions Department. “Her experience advising clients on large-scale renewable energy projects, combined with her practical approach to real estate and project development matters, will further strengthen the group’s ability to serve clients across the clean energy sector.”
Maria has extensive experience representing clients across the United States in large-scale real estate matters, with a particular focus on renewable energy and complex, multi-site acquisitions spanning industrial, retail, and office properties nationwide. Her practice encompasses utility-scale renewable energy projects, leasing, acquisitions, and dispositions. She regularly represents clients developing utility-scale wind and solar projects, guiding them through the full range of issues these developments present, including title, access, easements, and leasing.
Davis Graham’s Clean Energy & Sustainability Group advises clients on clean energy projects from start to finish, including project siting and permitting, and contractual agreements. The group’s work spans wind, solar, geothermal, green hydrogen, biomass, renewable natural gas, hydrogen, renewable energy storage, and carbon capture, use, and sequestration.
BLM Issues Curative NEPA Analysis for Wyoming Leases Subject to WildEarth Guardians and Western Watersheds Project Litigation
On June 5, 2026, the Bureau of Land Management (BLM) Wyoming State Office released a long-awaited environmental assessment (EA) intended to cure National Environmental Policy Act (NEPA) deficiencies affecting hundreds of federal oil and gas leases in Wyoming sold between 2015 and 2020. The EA supplements the NEPA analysis for the May 2015, August 2015, November 2015, February/May 2016, August 2016, November 2016, February 2017, June 2017, September 2017, September 2018, March 2019, and March 2020 Wyoming lease sales.
Environmental groups challenged these lease sales in WildEarth Guardians v. Haaland, No. 1:16-cv-01724 (D.D.C.) (“WEG I”), WildEarth Guardians v. Haaland, No. 1:20-cv-00056 (D.D.C.) (“WEG II”), WildEarth Guardians v. Haaland, No. 1:21-cv-00175 (D.D.C.) (“WEG III”), and Western Watersheds Project v. Haaland, No. 1:18-cv-00187 (D. Idaho). The supplemental NEPA analysis was required either because a court found error in BLM’s original analysis or through settlement agreements. The EA provides additional analysis on the effects of leasing on greenhouse gas emissions and greater sage-grouse, among other resources.
The EA has two significant consequences for federal oil and gas lessees in Wyoming. First, it allows BLM to resume approving applications for permit to drill (APDs) on leases covered by the EA. Second, it may cause lease suspensions to terminate. BLM had suspended leases subject to the WEG and Western Watersheds Project cases upon lessees’ request. Lessees should review their suspension terms carefully to determine whether the EA’s issuance caused suspensions to terminate automatically and primary terms to resume running.
Notably, the EA does not address lease sales challenged in Montana Wildlife Federation v. Burgum, No. 4:18-cv-00069-BMM (D. Mont.), which include the December 2017, March 2018, June 2018, February 2019, September 2019, December 2019, and December 2020 Wyoming lease sales. The Montana Wildlife Federation court has canceled most of these leases, rendering them ineligible for curative NEPA analysis.
District of Montana Vacates Oil and Gas Leases in Phase III of Montana Wildlife Federation
On June 12, 2026, the U.S. District Court for the District of Montana adjudicated the third phase of challenges to federal oil and gas lease sales in Montana Wildlife Federation v. Burgum, No. 18-cv-0069 (D. Mont.). The court found that, when deciding to lease, BLM did not properly apply a directive in its resource management plans (RMPs) requiring it to prioritize oil and gas leasing and development outside of sage-grouse habitat. As a result, the court vacated all nonproducing leases sold at the March and December 2019 Montana/Dakota lease sales and the February, September, and December 2019 Wyoming lease sales. The court declined to vacate nine producing leases from these sales and did not vacate BLM’s offering of parcels at the December 2020 Wyoming lease sale.
This decision aligns with prior rulings in the case. In Phase I (2020) and Phase II (2022), the court similarly vacated oil and gas leases after finding BLM failed to comply with the prioritization directive. The Ninth Circuit affirmed the Phase I decision, and an appeal of the Phase II decision is pending.
The Phase III decision is notable not only for vacating a broad swath of oil and gas leases but for sparing nine producing oil and gas leases. The court declined to vacate only those leases on which actual production, i.e., drilling, occurred. Leases held by communitized or unitized production, but on which drilling had not occurred, were vacated.
The court also declined to vacate BLM’s decision to offer leases at the December 2020 Wyoming lease sale. The court reasoned that, because BLM had not issued these leases, no final agency action existed that the court could vacate. The court expressly allowed BLM to complete further NEPA analysis to determine whether to issue these leases.
For the vacated leases, BLM will not immediately return monies to leaseholders. The court stayed the effectiveness of its decision to allow for appeals. As of July 15, 2026, no appeals have been filed.
Although the decision invalidates thousands of acres of existing leases, it may have a limited effect on future leasing. The prioritization directive was contained in BLM’s 2015 RMPs for greater sage-grouse management. BLM has since revised these RMPs, and the revised RMPs lack a prioritization directive. Moreover, Public Law 119-21 (2025), colloquially known as the One Big Beautiful Bill Act, requires BLM to offer for lease any lands designated as open for leasing in an RMP that received a nomination.
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.